If you’ve ever tracked your personal spending in a spreadsheet, listing income on one side and expenses on the other, you’ve already had a taste of what an accounting ledger does for businesses. Only, instead of a simple spreadsheet, a business ledger organizes all financial transactions in a structured way, ensuring that money coming in and going out is properly recorded.
For small businesses, understanding what an accounting ledger is and how it works isn’t just a bookkeeping chore, it’s a foundation for making better decisions, managing growth, and staying compliant.
What Is an Accounting Ledger?
An accounting ledger is the master record of all a business’s financial transactions. Think of it as the backbone of your bookkeeping system.
Here’s the simplest way to understand it:
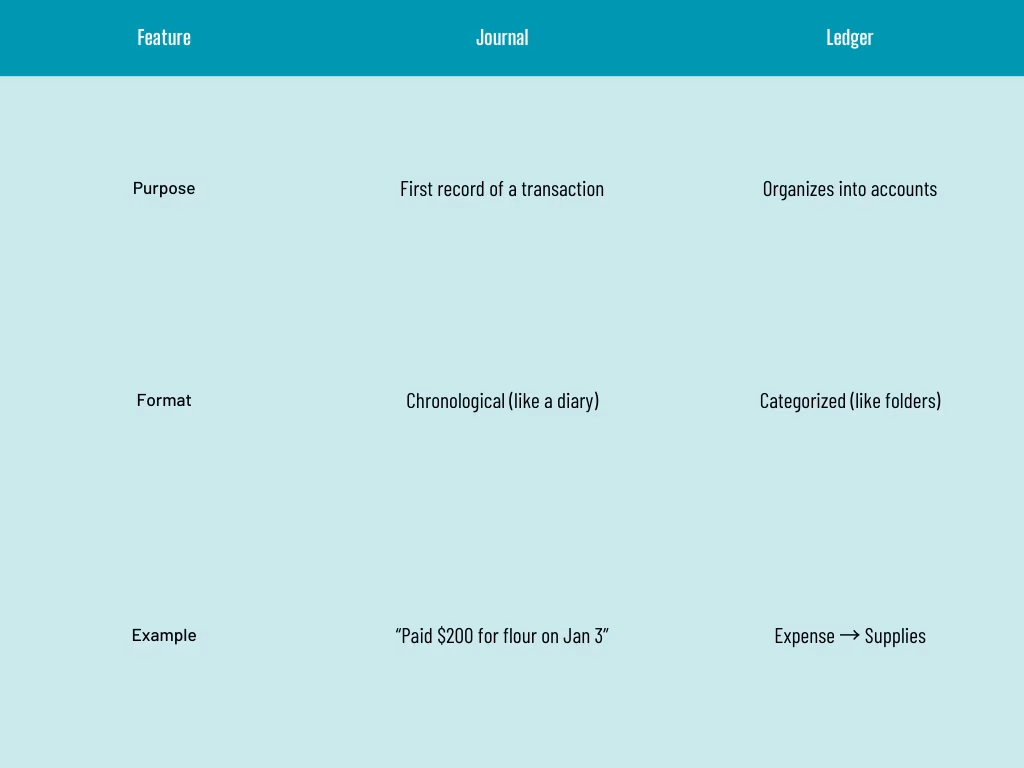
- Journal entries record transactions in chronological order (like a diary).
- The ledger takes those entries and organizes them into accounts (assets, liabilities, income, expenses, and equity).
So instead of sifting through hundreds of transactions, you can look at your ledger accounts and instantly see how much you’ve earned, spent, or owe in a specific category.
The General Ledger: The Heart of Accounting
When people say “ledger,” they usually mean the general ledger.
General Ledger Meaning
The general ledger (GL) is the central hub where every financial transaction gets sorted into categories (accounts). These categories typically include:
- Assets: Cash, accounts receivable, equipment
- Liabilities: Loans, accounts payable, taxes owed
- Equity: Owner’s capital, retained earnings
- Revenue (Income): Sales, service fees, interest earned
- Expenses: Rent, salaries, utilities, office supplies
Every entry in your accounting system eventually makes its way into the general ledger.
General Ledger Example
Let’s say you run a small bakery. Here’s what a week might look like in your general ledger:
- Monday: Sold $1,000 worth of pastries (Revenue → Sales account).
- Tuesday: Paid $200 for flour and sugar (Expense → Supplies account).
- Wednesday: Received $500 from a catering client (Revenue → Accounts receivable → Cash).
- Friday: Paid $800 in employee wages (Expense → Payroll account).
Each of these transactions appears in the ledger under the right category, updating your balances.
This way, you don’t just know that $1,500 came in and $1,000 went out, you know where it came from and why it went out.
Ledger vs. Journal: What’s the Difference?
It’s easy to confuse the two, but here’s a quick breakdown:
Why Is the Ledger Important?
Without an organized ledger, your books become a mess. Here’s why it matters:
- Tracks Financial Health
- Quickly see how much you’ve earned or spent in a category.
- Quickly see how much you’ve earned or spent in a category.
- Supports Accurate Reporting
- Essential for preparing financial statements (profit & loss, balance sheet).
- Essential for preparing financial statements (profit & loss, balance sheet).
- Ensures Compliance
- Auditors and tax authorities rely on ledger accuracy.
- Auditors and tax authorities rely on ledger accuracy.
- Improves Decision-Making
- Shows patterns in income and expenses.
- Shows patterns in income and expenses.
- Prevents Fraud and Errors
- Every transaction leaves a trace in the ledger.
Read More: What Is a General Ledger? Your Complete Overview
Types of Ledgers in Accounting
While the general ledger is the big picture, businesses also maintain subsidiary ledgers for detail:
- Sales Ledger (Accounts Receivable): Tracks money owed by customers.
- Purchase Ledger (Accounts Payable): Tracks money owed to suppliers.
- Cash Ledger: Records all cash transactions.
- Inventory Ledger: Tracks goods bought and sold.
These sub-ledgers roll up into the general ledger, keeping things organized.
General Ledger Accounting: How It Works
The process is straightforward (but detail-heavy):
- Record transaction in the journal.
Example: Bought $200 of flour. - Post transaction to the general ledger.
Debit Supplies Expense → $200.
Credit Cash → $200. - Update balances for each account.
- Prepare a trial balance (to check accuracy).
This is called double-entry accounting, for every debit, there’s a credit.
How to Create a General Ledger
If you’re a beginner, here’s how to set one up:
- Choose your accounting method
- Cash basis (simple) or accrual basis (more accurate).
- Cash basis (simple) or accrual basis (more accurate).
- Set up your chart of accounts
- Define categories: assets, liabilities, revenue, expenses.
- Define categories: assets, liabilities, revenue, expenses.
- Record opening balances
- Start with what you already have (cash, debt, equity).
- Start with what you already have (cash, debt, equity).
- Post transactions regularly
- Don’t let receipts pile up, record daily or weekly.
- Don’t let receipts pile up, record daily or weekly.
- Reconcile monthly
- Match ledger balances with bank statements.
- Match ledger balances with bank statements.
Pro Tip: Use cloud software or AI tools to automate postings and avoid human error.
Modern Tools: Accounting Ledgers in the Cloud
Gone are the days of handwritten ledgers. Today, businesses use cloud-based accounting software that updates ledgers in real time.
Benefits of cloud and AI-powered ledgers:
- Auto-categorization of expenses
- Real-time financial dashboards
- Easy collaboration with accountants
- Reduced risk of errors
This is where Otto AI stands out, by automating tedious ledger management while giving you insights into spending patterns and profitability.
Common General Ledger Mistakes (and How to Avoid Them)
- Not Reconciling Accounts
- Always match ledger balances with bank accounts.
- Always match ledger balances with bank accounts.
- Mixing Business and Personal Expenses
- Keep them separate for accuracy and tax compliance.
- Keep them separate for accuracy and tax compliance.
- Skipping Adjusting Entries
- Record depreciation, prepaid expenses, and accruals correctly.
- Record depreciation, prepaid expenses, and accruals correctly.
- Data Entry Errors
- Typos can throw off entire reports, AI automation prevents this.
- Typos can throw off entire reports, AI automation prevents this.
- Overlooking Sub-Ledgers
- Forgetting to update AR or AP leads to mismatches.
- Forgetting to update AR or AP leads to mismatches.
Accounting Ledger Example (Step by Step)
Imagine a small consulting firm:
- Transaction 1: Invoice client $2,000 for services.
- Debit Accounts Receivable $2,000
- Credit Service Revenue $2,000
- Debit Accounts Receivable $2,000
- Transaction 2: Pay office rent $500.
- Debit Rent Expense $500
- Credit Cash $500
- Debit Rent Expense $500
- Transaction 3: Client pays $2,000 invoice.
- Debit Cash $2,000
- Credit Accounts Receivable $2,000
- Debit Cash $2,000
After posting these, the ledger shows updated balances in Cash, Accounts Receivable, Revenue, and Rent Expense.
General Ledger vs. Trial Balance
Another common point of confusion:
- General Ledger: Detailed record of all accounts.
- Trial Balance: A report that ensures total debits = total credits.
The trial balance is essentially a checkpoint pulled from the ledger.
How AI Is Transforming Ledger Management
AI is changing accounting ledgers in big ways:
- Auto-classification of transactions (saves hours).
- Error detection (flags duplicates or missing entries).
- Smart forecasting (predicts cash flow from ledger data).
- Seamless integration with banks and invoices.
With Otto AI, you don’t just record transactions, you get actionable insights from your ledger data.
Conclusion
An accounting ledger isn’t just bookkeeping, it’s the financial map of your business. By organizing transactions into categories, it helps you track health, prepare reports, and make informed decisions.
While the concept has been around for centuries, modern businesses don’t have to manage ledgers by hand. With AI-powered tools like Otto AI, you can streamline ledger management, prevent errors, and focus more on growth than on spreadsheets.